Hello, I’m Thomas Park.
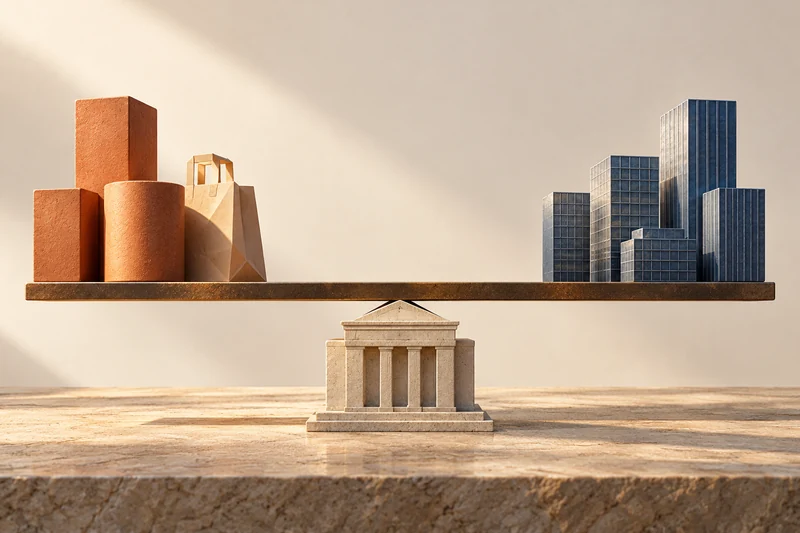
On September 15–16 (local time), the U.S. Federal Reserve held a Federal Open Market Committee (FOMC) meeting and raised its benchmark interest rate by 0.25 percentage points, from 3.50–3.75% to 3.75–4.00%. The move had been signaled since three policymakers dissented in favor of a rate hike at the July FOMC meeting, but its implementation has ushered in a new phase for markets.
This was the first rate hike in about three years and two months, since July 2023. Just as it seemed the rate-cutting cycle was over, the Fed reached for the tightening lever again. Today, I’ll look at the reasons behind the decision and where the U.S. economy may be headed in the fourth quarter of 2026.
Why Did the Fed Raise Rates Again?
The rate hike did not come out of nowhere. Signs had been clear since the summer.
At the July FOMC meeting, the Fed held rates steady for the fifth consecutive time but made its hawkish stance clear. Three of the 12 policymakers dissented in favor of a 0.25-percentage-point hike—the most dissents of this kind since 1979. Chair Kevin Warsh emphasized the Fed’s commitment to price stability, saying, "Inflation remains elevated relative to our 2% target."
After that, the balance shifted sharply toward a hike. Rising oil prices amid tensions in the Middle East added to inflationary pressures, while core consumer inflation came in above market expectations. The probability of a September hike topped 86% and surged to 92–94% just before the meeting. Major investment banks, including Goldman Sachs, JPMorgan, and HSBC, also unanimously forecast a hike.
Interestingly, some see this move as being more about “credibility” than inflation itself. Underlying core inflation has been slowing, and some argue that tariff-driven price increases are temporary. Goldman Sachs and Standard Chartered therefore supported holding rates steady. The Fed’s decision to hike can be seen as an effort to prevent inflation expectations from taking root again and reinforce its commitment to price stability.
Markets Should Focus on the Rate “Path,” Not the “Level”
More important than the rate hike itself at this FOMC meeting are the accompanying dot plot and Chair Warsh’s communications.
Here is how markets are thinking about it: If the hike was limited to the expected 0.25 percentage points, it could be seen as removing uncertainty. But the picture changes if the Fed strongly signals the possibility of further hikes. The 10-year U.S. Treasury yield has already topped 5%, its highest level since 2007, and further tightening signals could weigh on both bond and stock markets.
Throughout the fourth quarter, markets will grapple with the question: “Was this hike a one-time insurance move, or the start of a new hiking cycle?” The answer will determine the direction of asset markets in the fourth quarter.
Three Things to Watch in the U.S. Economy in Q4 2026
First, the burden of prolonged high interest rates on the real economy.
A return to a 4% benchmark rate means higher borrowing costs for businesses and households. Companies facing maturing corporate bonds issued during the low-rate era, as well as small and midsize businesses with a high share of floating-rate debt, will face a heavier interest burden. Higher mortgage rates could also once again dampen activity in the housing market. The key question ahead of the fourth-quarter holiday shopping season, from Thanksgiving through year-end, is how well household purchasing power holds up.
Second, the outlook for oil prices and inflation.
The trigger for this hike was rising oil prices driven by developments in the Middle East. If oil prices stabilize in the fourth quarter, inflationary pressure will ease and the case for further Fed hikes will weaken. But if geopolitical tensions persist and energy prices rise again, discussions of another hike could intensify at the December FOMC meeting. Oil prices are by far the biggest external variable for the U.S. economy in Q4.
Third, whether the labor market shows signs of strain.
If efforts to tame inflation through tightening damage employment, the Fed will once again face a dilemma. As the debate over slowing employment data this summer showed, the labor market can cool gradually before suddenly deteriorating. If rate hikes lead to weaker hiring and rising layoffs in the fourth quarter, markets will begin pricing in concerns about a “policy mistake.”
Q4 Outlook by Scenario
Scenario 1: One-Time Hike Followed by a Wait-and-See Approach (Most Likely)
This scenario assumes the hike is a form of insurance and oil prices stabilize. The Fed responds by holding rates steady in December, and markets could stage a relief rally. Despite slower growth, the economy stays on a soft-landing path and avoids recession.
Scenario 2: A New Rate-Hiking Cycle
This scenario assumes rising oil prices and a rebound in inflation persist, prompting another hike in December. Treasury yields rise further, and the stock market could face a deeper correction, led by growth stocks with high valuations. The dollar strengthens again, increasing pressure on capital outflows from emerging markets.
Scenario 3: A Sharp Slowdown from Excessive Tightening
In this scenario, the effects of the hike cool the real economy faster than expected. If labor market deterioration becomes clear, the Fed will have to reverse course sharply, and market volatility will surge. The probability is low, but this tail risk cannot be ruled out.
A Note for Korean Investors
The wider gap between U.S. and Korean benchmark interest rates following this hike could put upward pressure on the won and increase import costs. In fact, the won-dollar exchange rate topped 1,370 ahead of the FOMC meeting. Since capital flows tied to U.S. interest rates can increase volatility in South Korea’s financial markets, investors should review their currency hedging and exposure to dollar-denominated assets.
For investors in U.S. assets, first, safe assets that offer high yields, such as short-term Treasuries and money market funds, have become more attractive again. Second, investors should consider the relative resilience of high-quality value stocks with solid cash flow over interest-rate-sensitive growth stocks. Third, volatility could recur with each data release through the December FOMC meeting, so investors should stick to a dollar-cost averaging approach.
In Closing
The first rate hike in three years and two months carries a clear message: “The war on inflation is not over.”
But I don’t think there’s a need to interpret this hike too pessimistically. Paradoxically, the fact that the Fed can raise rates also suggests it believes the U.S. economy can withstand that level of tightening. The question is whether that judgment is correct—a question the fourth-quarter data will answer.
Oil prices, inflation, and employment. The combination of these three indicators will determine the direction of the U.S. economy and global markets in the fourth quarter of 2026. I’ll be watching closely with you until the December FOMC meeting.
I look forward to sharing a deeper analysis in my next column.
 This image is temporarily unavailable.
Questions about this story?
AI answers only from this article and related ones.
Answered from ten years of our reporting. Check legal and tax questions with a professional.